Best Money Apps 2026: 7 Picks to Master Your Cash
Choosing the best money apps is no longer a luxury — it is how modern households stay ahead of rising costs. In 2026, the average smartphone owner juggles three or four financial apps, from a budgeting tracker to a payment tool to an investing platform. The trick is not downloading more; it is picking the right one for each job.
This roundup groups my favorite apps by purpose so you can build a lean toolkit without the clutter. I have tested each personally across a full year of real bills, paychecks, and impulse buys.
How I Chose These Apps
Not every shiny app earns a spot on your home screen. I weighed four factors that separate genuinely useful tools from noisy ones.
- Cost: Low or no fees, with transparent pricing.
- Security: Encryption, biometric locks, and clear insurance disclosures.
- Ease of use: A clean interface a first-timer can navigate.
- Real impact: Features that actually change behavior, not just dashboards.
Best Money Apps by Category
Here is how the top picks stack up. Think of this as a starter map rather than a mandate — you rarely need more than one app per column.
| Category | Best For | Standout Feature |
|---|---|---|
| Budgeting | Zero-based planners | Every dollar assigned a job |
| Payments | Splitting bills fast | Instant $Cashtag transfers |
| Saving | Automatic savers | Round-ups and goal buckets |
| Investing | Beginners | Fractional shares from $1 |
| Credit | Score builders | Free monitoring and alerts |
For Budgeting
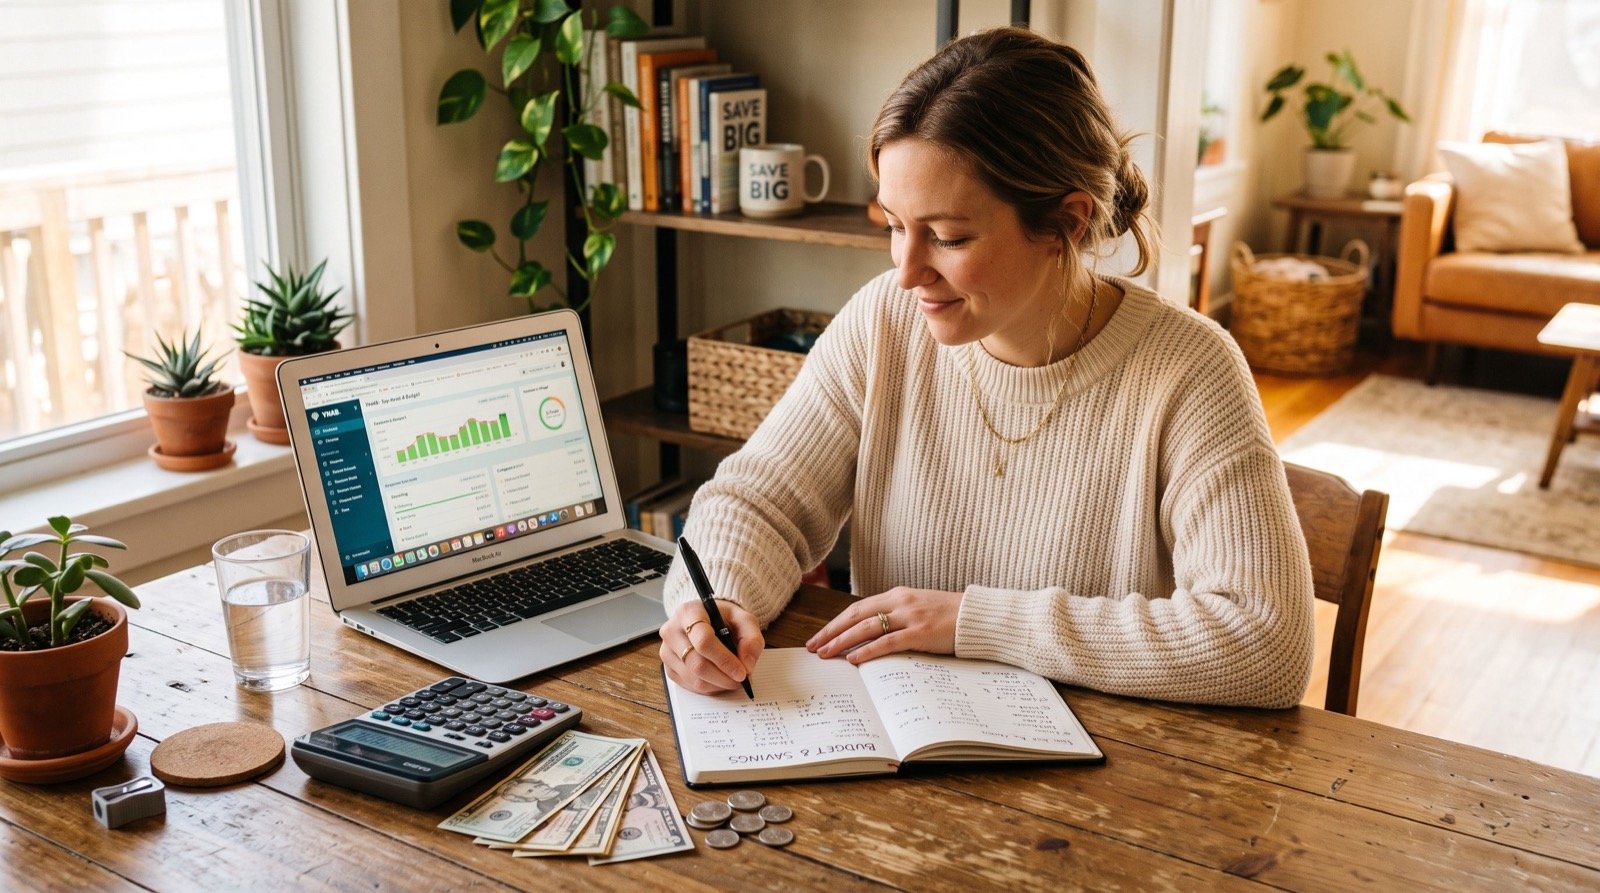
A zero-based budgeting app forces you to give every dollar a purpose before the month begins. This single habit exposes leaks — the forgotten subscription, the creeping food-delivery bill — faster than any spreadsheet.
For Payments
Peer-to-peer payment apps have replaced the ATM run. If you want a full breakdown of setup and fees, a dedicated Cash App guide walks through direct deposit, the Cash Card, and how to avoid instant-transfer charges.
For Saving and Investing
Round-up savers sweep spare change into a separate balance, while beginner investing apps let you buy fractional shares of major companies. Together they turn small, painless amounts into real momentum over a year.
For Credit Building
Free credit-monitoring apps show your score, explain what moves it, and alert you to suspicious activity. Seeing the number update after an on-time payment is a surprisingly effective motivator, and the alerts help you catch identity theft early.
Some apps go further, reporting your rent or utility payments to the bureaus so responsible habits you already have finally count toward your score. For renters with a thin credit file, that single feature can be transformative.
Which Money App Should You Download First?
If you are starting from scratch, resist the urge to install all seven at once. Follow this order so each new tool builds on the last instead of overwhelming you.
- Start with a budgeting app to see where your money actually goes.
- Add a payment app for splitting shared costs and getting paid quickly.
- Turn on an automatic saver to build a cushion without thinking.
- Introduce a beginner investing app once you have an emergency fund.
- Layer in free credit monitoring to protect your score.
Sequencing matters. A saver app is far more effective after a budget reveals how much you can safely set aside.
Security: The Non-Negotiable Feature
Convenience means nothing if your account is exposed. The U.S. Federal Deposit Insurance Corporation notes that funds in nonbank payment apps are not automatically insured the way a bank deposit is, so read each app’s disclosures carefully. Their consumer resources are available at the FDIC Consumer Resource Center.
For safe-handling habits across every app you use, the Consumer Financial Protection Bureau publishes plain-language tools worth bookmarking. My rule is simple: enable biometric locks everywhere, keep balances modest in uninsured apps, and never store more than you would carry in cash.
Common Mistakes to Avoid With Money Apps
Even the best toolkit backfires when used carelessly. After watching friends and family adopt these apps, I see the same avoidable errors again and again.
The first is app overload — installing a dozen tools, checking none of them, and ending up more confused than before. The second is treating a payment app like a savings vault; uninsured balances should stay lean. The third is ignoring notifications, which are your early-warning system for both fraud and overspending.
A subtler mistake is chasing sign-up bonuses without reading the fine print. A $20 promo means little if the app charges monthly fees or nudges you toward high-risk trades. Judge each tool by how it changes your behavior over a full year, not by its launch-week incentive.
Making the Apps Work Together
The real magic appears when your apps talk to one another. Route your paycheck through direct deposit, let the budgeting app categorize it, and schedule automatic transfers to savings on payday. This “set and forget” pipeline removes willpower from the equation.
Life transitions are a perfect stress test. When my family planned a downsizing move, we paired a shared budget with quick app payments to the reputable service experts managing our storage, and every cost stayed transparent. Curating the best money apps for your situation turns chaotic spending into a calm, repeatable system.
Frequently Asked Questions
Are money apps safe to link to my bank?
Reputable apps use bank-level encryption and tokenization, meaning your real account number is hidden. Stick to well-known publishers, enable biometric locks, and review permissions before linking.
How many money apps do I really need?
Most people thrive with three: one budgeting app, one payment app, and one savings or investing app. Adding more than that usually creates confusion rather than clarity.
Do budgeting apps cost money?
Some are free with ads or basic features, while premium planners charge a monthly or annual fee. Try a free tier first and only upgrade if the paid features clearly change your habits.
Can money apps help improve my credit score?
Yes. Several apps offer free credit monitoring, spending insights, and on-time payment reminders. They cannot fix your score overnight, but consistent alerts help you avoid the late payments that hurt it.
The Bottom Line
The best money apps are the ones you actually open. Start with a budget, add a payment tool, automate savings, and protect every login. Build that lean stack in 2026 and you will spend less time worrying about money and more time putting it to work.